Atradius Atrium
Get direct access to your policy information, credit limit application tools and insights.

 Group
 Australia
 Austria
 Belgium
 Brazil
 Bulgaria
 Canada
 China
 Czech Republic
 Denmark
 Finland
 France
 Germany
 Greece
 Group
 Hong Kong SAR
 Hungary
 India
 Ireland
 Italy
 Japan
 Lithuania
 Mexico
 Netherlands
 New Zealand
 Norway
 Poland
 Portugal
 Romania
 Singapore
 Slovakia
 Slovenia
 Spain
 Sweden
 Switzerland
 Turkey
 United Arab Emirates
 United Kingdom
 United States
We have released an updated industry forecast per market for Q4 2026, providing business performance and credit risk assessments from our underwriters. The chart covers key sectors across representative markets in Europe, the Americas, and Asia-Pacific, reflecting global economic activity.
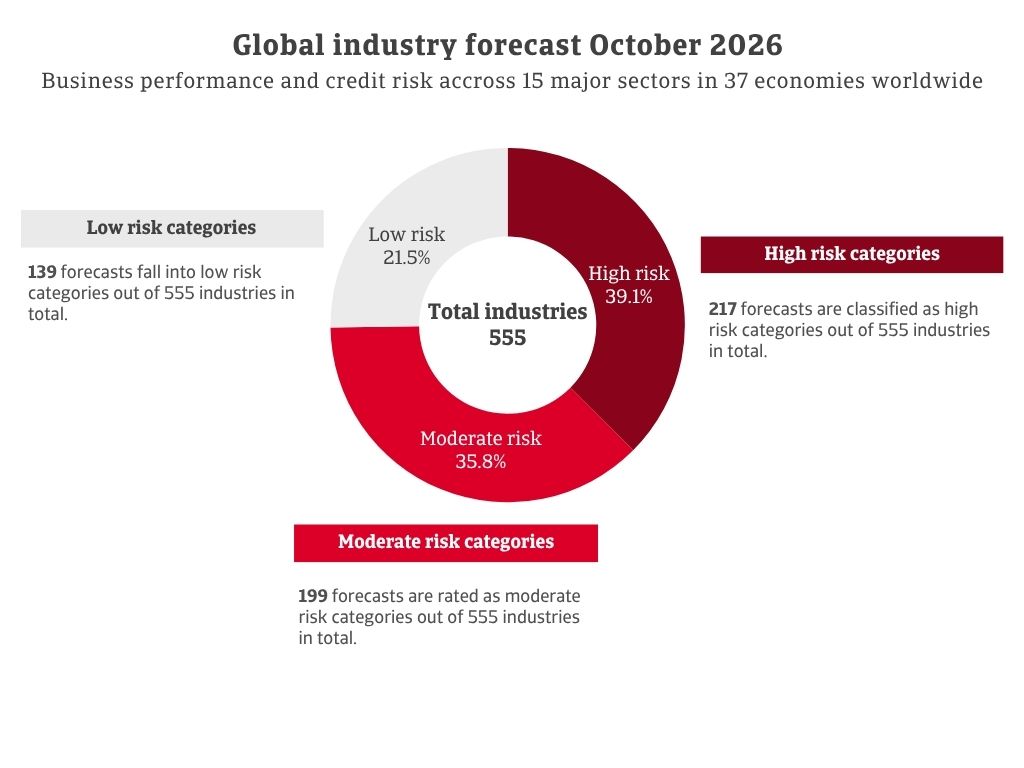
In total, we have issued 555 forecasts. Of these, 139 fall into low-risk categories, 199 are rated as moderate risk, and 217 fall into the high-risk category. This represents an increase of 23 sectors in the high-risk group since January 2026.
Forecasts for food, pharmaceuticals, financial services, electronics/ICT, and agriculture are more favourable than the overall benchmark. Machines/engineering and services remain at mid-range risk levels. Transport, automotive, consumer durables, and paper show elevated risk. The most negative outlook is concentrated in construction, metals/steel, and textiles.
French metal and steel producers face increasingly difficult conditions. Higher input prices are putting more pressure on margins and working capital. Demand remains weak, particularly from the automotive and construction, which are key buyer. Excess global capacity and intense competition are also affecting trading activities. However, higher metal prices supported recycling businesses in the first half of 2026.
We expect agricultural output to fall by 8.5% this year. Recurring droughts and water shortages have negatively affected crop production. Energy, fertiliser, feed and financing costs remain high. In the meat sector, the pork segment faces rising costs, labour shortages, and disease concerns. These pressures are weakening margins. We expect credit insurance claims in the agricultural sector to increase in the coming months.
We expect Hungarian food production to fall by 3.3% this year. Recent high food inflation has reduced consumers’ purchasing power and held back domestic sales volumes. Local processors face strong competition from foreign brands. Large retail chains also have considerable bargaining power, putting further pressure on margins. Competition is particularly intense in the fast-moving consumer goods (FMCG) segment. This puts Hungarian businesses at a disadvantage compared with larger foreign competitors.
Artificial intelligence, cloud services and continued digitalisation are attracting substantial investment. In 2025, 33% of Dutch businesses used at least one of eight measured artificial intelligence technologies. This share increased from 23% in 2024. We expect information and communication output to grow by 3.6% this year. Continued investment in data centres is supporting electronics and information and communication technology businesses.
Portugal’s consumer durables sector benefits from a moderately favourable environment. Private consumption is forecast to grow by 3.1% in 2026. We expect consumer durables sales to increase by 4.4%. This follows subdued performance over the past three years. However, high housing and living costs continue to put pressure on household budgets. Global uncertainty could also weaken consumer confidence and spending.
We expect pulp and paper production to remain broadly unchanged in 2026 and 2027. Demand remains resilient in some segments, but producers face significant cost pressures. The war in the Middle East has increased pressure on margins due to higher energy, chemical, and freight costs. Strong competition from Asian producers makes it harder for companies to pass these costs to customers. The sector also requires substantial capital investment. Rising financing costs and falling revenues in Spain and Europe are adding pressure.
Spain’s transport sector continues to face significant challenges. Rising fuel and labour costs are putting pressure on profitability. Strong competition adds further pressure. Operators must also invest to meet environmental and decarbonisation targets. While demand remains resilient and supports moderate growth, many operators continue to struggle with tight margins.
The Atradius industry forecast by market provides an expert view of business performance and credit risk across different sectors and geographies. It covers 15 major industries in 37 representative economies.
Each sector-market combination is assigned an opinion - excellent, good, fair, poor, or bleak - based on the insights of Atradius specialised risk analysts.
These underwriters work from centres of expertise around the world, ensuring that every assessment reflects local realities and is informed by on-the-ground knowledge. This approach highlights the strength of Atradius' risk management system and its ability to anticipate challenges in global trade.
Important note: While the chart offers a powerful overview, it is important to remember that risk does not reside in countries or sectors but in individual buyers. That is the true value of credit insurance: the ability of our underwriters to deliver a guaranteed, near-instant opinion on virtually any buyer worldwide, enabling businesses to trade with confidence.
To explore to strengthen your own credit risk strategy, get in touch with us and see how we can help you stay ahead.